Corporate NPS allows employees to build their retirement savings through the National Pension System with their employer playing a role in the contribution process.
The underlying NPS account remains your account, but it is linked to your employer under the Corporate Sector. This allows contributions to be facilitated through the employer’s payroll process, while you continue to build your retirement corpus.
So, how does Corporate NPS work for an employee? The process typically involves checking whether your employer offers Corporate NPS, opening or mapping your NPS account, completing employer approval and setting up contributions through payroll.
How Does Corporate NPS Work for an Employee?
1. Check if your employer offers Corporate NPS
The first step is to check with your employer whether Corporate NPS is available as an employee benefit.
You can join NPS under the Corporate Sector only if your employer has enabled the benefit. If your organisation has not adopted Corporate NPS, you cannot independently open an account under its Corporate Sector arrangement.
Your HR or payroll team should be able to confirm whether the benefit is available and, if so, explain the process followed by your organisation.
2. Open your NPS account under the Corporate Sector
If your employer offers Corporate NPS, you can create your NPS account through the service provider associated with your employer.
For example, if your organisation uses Floatr, you can open your Corporate NPS account through the Floatr app in under 5 minutes.
During account opening, you will generally need to:
- Complete your KYC
- Select your employer
- Enter the required employment details
- Select your NPS investment options
- Complete the account-opening process
Once the required details are submitted, your NPS account and PRAN (Permanent Retirement Account Number) are generated instantly.
Do you need to invest money to open the account? No initial investment is required to open a Corporate NPS account.
This is useful because you can complete the account-opening process first and then have contributions made through your employer’s payroll process.
With a digital account-opening process, the registration itself can typically take only a few minutes.
3. Employer approval completes the Corporate NPS setup
Opening the account is not the end of the process.
Since your NPS account is being registered under your employer’s Corporate Sector arrangement, the registration needs to be approved through the employer’s designated process. The person responsible for this within the organisation is commonly referred to as the Nodal Officer.
Once the registration is approved, your account is ready to receive Corporate NPS contributions.
This is the key difference from opening an NPS account independently: your employer becomes part of the administrative and contribution process.
4. Already have an NPS account? You don’t need another one
If you already have an active NPS account and therefore already have a PRAN, you do not need to create a second NPS account simply because your employer is offering Corporate NPS.
Instead, your existing NPS account can be shifted or mapped to the Corporate Sector arrangement.
Depending on the service provider associated with your employer, this process may be available digitally. For example, through Floatr, the process can be completed in a few steps on the mobile app.
The actual time taken for the shift can vary. In some cases, particularly where the process involves an inter-CRA (Central Recordkeeping Agency) shift, it can take longer and may take up to around a week.
Once the shift is completed, the existing PRAN is ready for Corporate NPS contributions.
An important point: If shifting involves CRA shifting, your access to the existing CRA will cease to exist and you can access your NPS from the new CRA portal. For example, if your account shifts from Protean to KFIN CRA, you should login to CRA portal of KFIN instead of Protean after the shift. Your Protean login will be deactivated in this case.
5. Tell your payroll team how much you want to contribute
Opening or shifting your NPS account is only one part of the process.
You should also inform your HR or payroll team about your intended NPS contribution, as per your organisation’s process.
This declaration helps your employer know how much should be deducted from your salary, where applicable, and/or processed as an employer contribution.
The exact payroll process can vary from one organisation to another, so employees should follow the instructions provided by their employer.
6. Your employer can then contribute to your NPS
Once your Corporate NPS account is active and the payroll process is set up, your employer can make contributions to your NPS account. You do not play further role in this process.
You can also continue making your own contributions to NPS.
This is one of the biggest advantages of Corporate NPS: your employer can contribute to your retirement account as part of the employer’s benefit structure.
Instead of relying only on your personal savings, Corporate NPS can therefore allow your retirement corpus to receive contributions from both you and your employer.
How are Corporate NPS contributions invested?
Once the contribution reaches your NPS account, it is invested according to the investment choices applicable to your account. The contribution becomes part of your NPS pension wealth and continues to participate in the performance of the selected investment option.Corporate NPS does not mean that your employer takes control of your investments.
Your NPS account continues to be yours, and you retain the ability to manage your NPS investment choices within the options available to you.
You can continue to make decisions around your:
- Investment allocation
- NPS schemes
- Pension fund manager, where choice is available
- Portfolio
The Corporate Sector primarily changes how the NPS account is connected to your employment and how contributions can flow through the employer. It does not turn your NPS account into an employer-owned account.
In short: How Corporate NPS works
The Corporate NPS journey can be simplified into these steps:
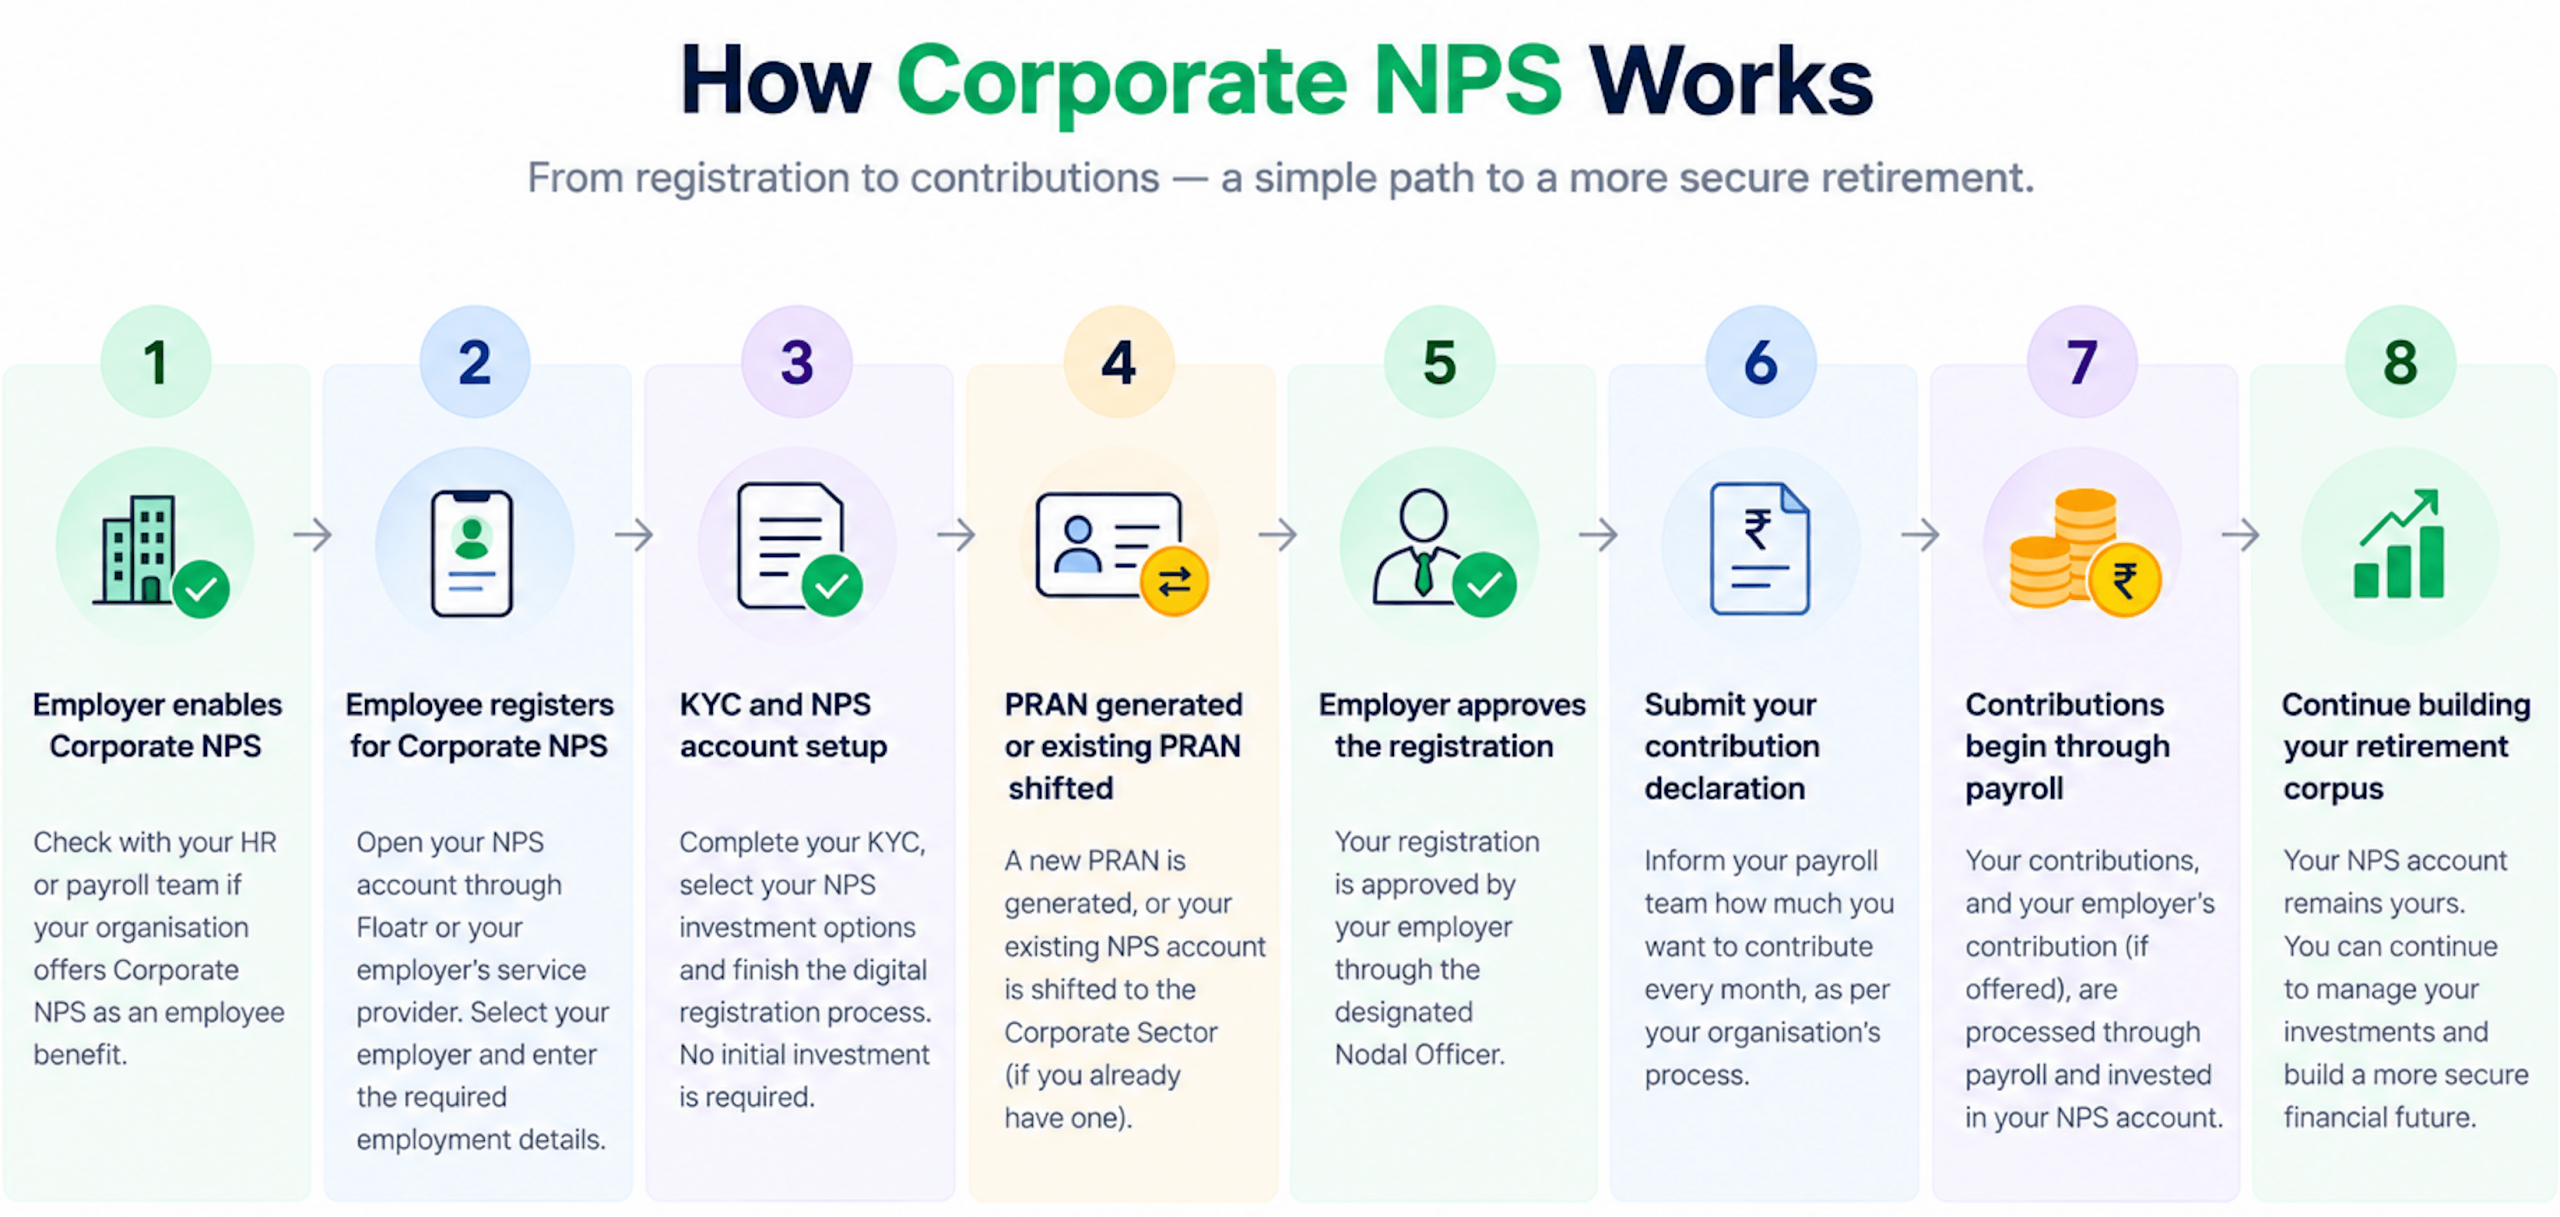
- Check whether your employer offers Corporate NPS
- Open your NPS account under the Corporate Sector
- Complete employer approval
- Shift or map your existing PRAN, if you already have an NPS account
- Submit your contribution declaration to your HR or payroll team
- Employer contributions begin through the payroll process
- Continue building your retirement savings
One NPS account. A simpler way to build retirement savings.
Corporate NPS essentially brings your NPS account into your workplace’s benefits and payroll ecosystem. Your account remains yours, while your employer can facilitate and contribute towards your retirement savings.
For employees whose organisations offer the benefit, the process of getting started can be relatively simple—and importantly, you don’t need to create a new PRAN if you already have an existing NPS account.
Frequently Asked Questions
1. How does Corporate NPS work?
Corporate NPS allows employees to invest in the National Pension System through their employer. The employee opens or maps an NPS account under the Corporate Sector, completes the employer’s approval process and provides the required contribution details to HR or payroll. Contributions can then be processed through the employer’s payroll system, with the employer also able to contribute as part of its employee benefit structure.
2. Can I open Corporate NPS if my employer does not offer it?
No. Corporate NPS is available to an employee only when the employer has enabled NPS under the Corporate Sector. If your organisation has not adopted Corporate NPS, you cannot independently open an account under that organisation’s Corporate Sector arrangement. You can, however, explore opening an NPS account independently under the applicable NPS model.
3. Do I need a new PRAN for Corporate NPS?
No. If you already have an active NPS account and a PRAN, you generally do not need to create another NPS account simply because your employer offers Corporate NPS. Your existing account can be shifted or mapped to the Corporate Sector arrangement, following the process applicable to your employer and service provider.
4. Can I use my existing NPS account for Corporate NPS?
Yes. An existing NPS account can be shifted or mapped to the Corporate Sector arrangement instead of opening a second account. The process may vary depending on the service provider and CRA associated with your employer. Once the process is completed, the same PRAN can be used for Corporate NPS contributions.
5. How are Corporate NPS contributions made?
Once the Corporate NPS account is active and the payroll process has been set up, contributions can be processed through the employer’s payroll system. The employee may need to declare the intended contribution to the HR or payroll team. Depending on the organisation’s benefit structure, contributions may be made by the employee, the employer, or both.
6. Can my employer contribute to my NPS account?
Yes. Under the Corporate Sector, an employer can contribute to an employee’s NPS account as part of its employee benefit structure. The contribution and payroll process will depend on the arrangement offered by the employer.
7. What are the tax benefits of NPS?
NPS can offer tax benefits on eligible contributions. Employer contributions to NPS can qualify for a tax deduction under the applicable provisions, while eligible employee contributions may also qualify for deductions depending on the tax regime and applicable rules. The actual tax benefit depends on factors such as your salary, contribution amount and the tax regime applicable to you.
8. What happens to my NPS if I change employers?
Your NPS account remains yours when you change employers. Changing jobs does not by itself mean that you need to withdraw your accumulated NPS corpus or create a new PRAN. If your new employer also offers Corporate NPS, your existing NPS account can be brought under the new employer’s Corporate Sector arrangement through the applicable process.
9. Can I choose how my Corporate NPS money is invested?
Yes. Corporate NPS does not mean that your employer owns or controls your NPS investments. Your NPS account remains yours, and you can manage your investment choices within the options available to you. Depending on the applicable NPS framework and choices available through your account, this can include investment allocation, NPS schemes and pension fund manager selection.
10. How can I open a Corporate NPS account through Floatr?
If your employer is empanelled with Floatr for Corporate NPS, you can open your Corporate NPS account directly through the Floatr mobile app in less than 5 minutes. The process is designed to make NPS onboarding simple and convenient for employees.
If you already have an existing NPS account, you can also apply to shift your existing NPS account to Corporate NPS through the Floatr app itself. The process can be completed in less than 2 minutes.
You can download the Floatr app on Android or iOS and get started.
The only requirement is that your employer should be empanelled with Floatr for Corporate NPS.