“My annual income is below ₹12 lakh. I don’t really save much tax through NPS. Should I still invest? Should I join my employer’s Corporate NPS programme?”
It’s a perfectly valid question. After all, NPS is often viewed primarily as a tax-saving investment. If the immediate tax benefit appears limited, many assume there is little reason to participate.
I believe that’s one of the biggest misconceptions about the National Pension System (NPS).
A retirement product should not be evaluated solely by the tax deduction it offers when you invest. It should be evaluated by how efficiently it helps you build wealth over the next 25 or 30 years. That’s where NPS stands apart. Its biggest strength isn’t just the tax benefit at the time of contribution, but the tax efficiency it offers throughout your entire investment journey—from investing and managing your portfolio to eventually withdrawing your retirement corpus.
What Are the Tax Benefits of NPS? Understanding the Triple Tax Advantage
Among the many retirement products available today, NPS tax benefits make the National Pension System one of the most tax-efficient investment options in India. NPS deserves a different lens because taxation influences far more than the decision to invest. Over a working life spanning two or three decades, you’ll contribute regularly, review your portfolio, rebalance your investments as your risk appetite changes, and eventually withdraw your retirement savings.
Each of these stages has tax implications.
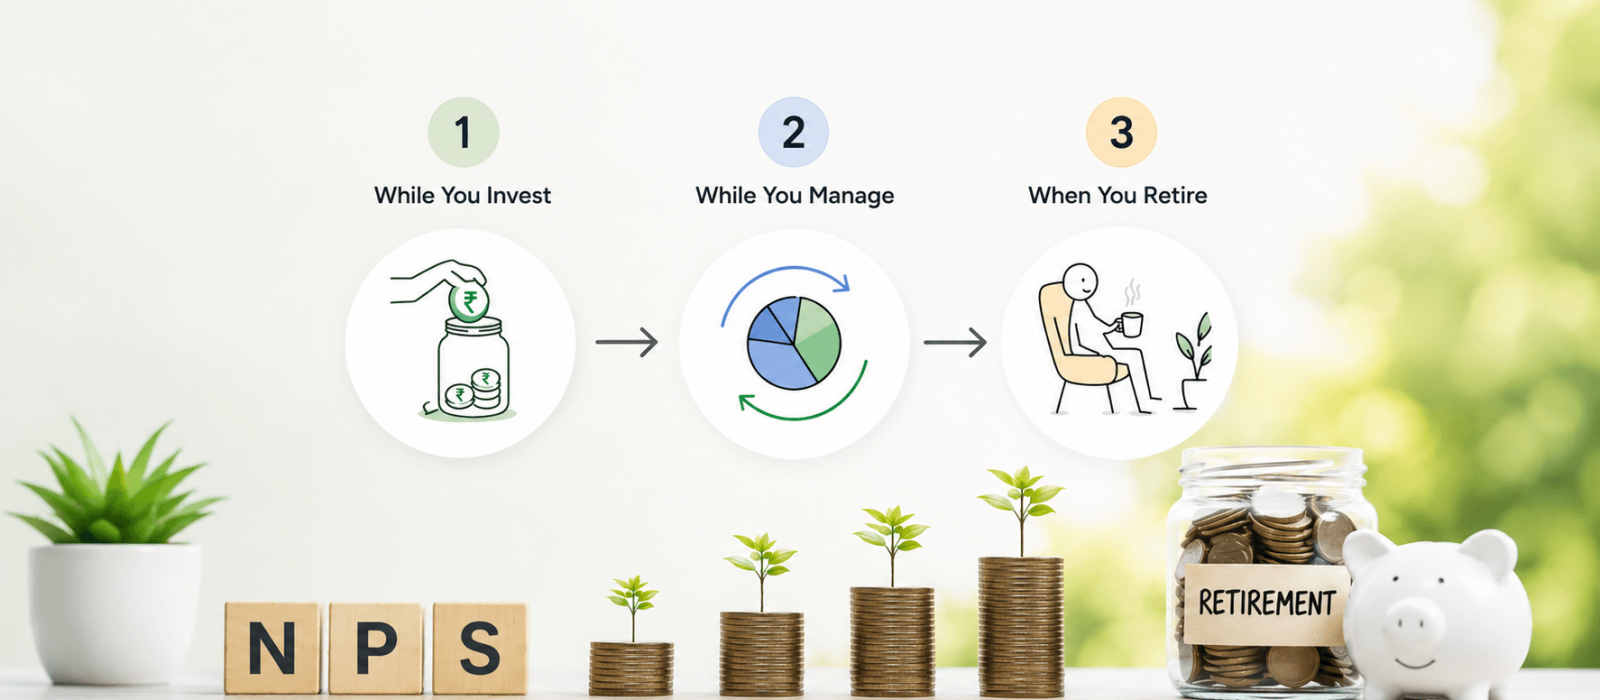
This is why I describe NPS as offering a Triple Tax Advantage—a framework that looks at tax efficiency across the entire investment journey rather than just at the point of entry. This is also referred to as Exempt-Exempt-Exempt (EEE), signifying tax advantages at three stages: contribution, accumulation, and withdrawal. However, while the EEE framework highlights the tax treatment across these three stages, it does not capture one equally important aspect of NPS. That additional factor, which further enhances the overall tax efficiency of NPS, is discussed in this section.
The first advantage comes when you invest through the tax deductions available under the prevailing provisions of the Income-tax Act. The second comes while you manage your portfolio, where permitted rebalancing within NPS does not trigger capital gains tax. The third comes at retirement, when withdrawals enjoy favourable tax treatment under the current regulations.
Individually, each of these benefits is valuable. Together, they make NPS one of the most tax-efficient retirement investment options available to Indian investors. 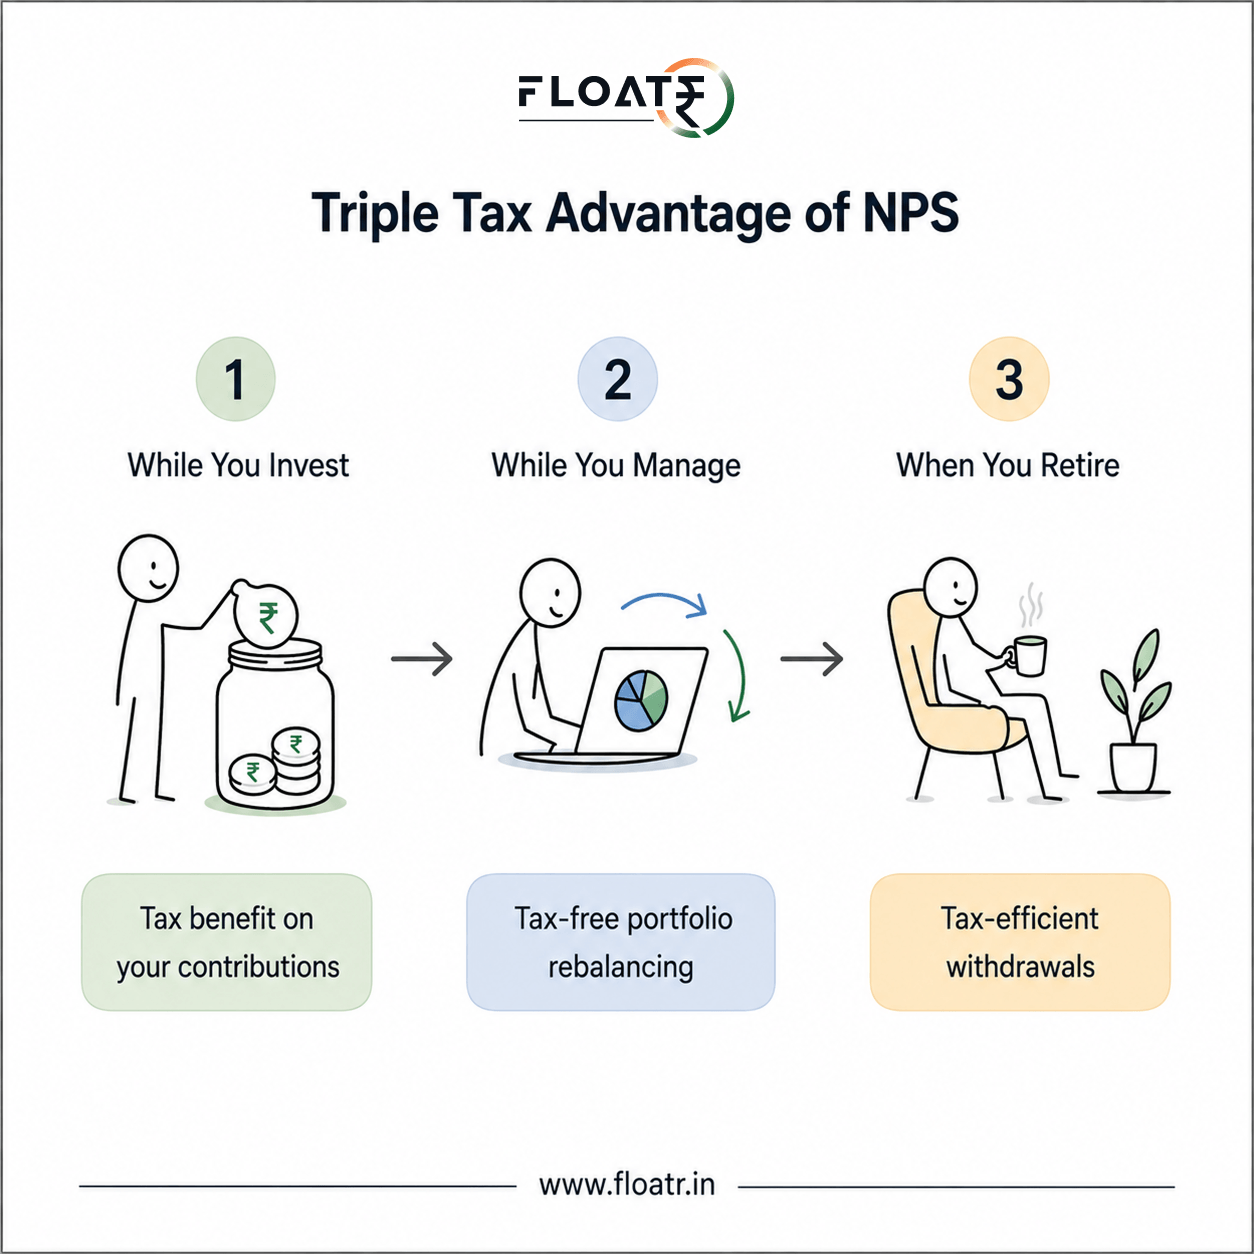
Tax Advantage #1: NPS Tax Benefits on Contributions
The first advantage of NPS is the one most investors are familiar with—tax savings at the time of contribution.
Individuals can claim tax deductions on eligible contributions under the applicable provisions of the Income-tax Act. Employees enrolled through their employer’s Corporate NPS programme may also receive additional tax benefits on employer contributions, subject to the prevailing tax rules. These incentives make NPS one of the most tax-efficient ways to begin building a retirement corpus.
NPS Tax Benefits and Deduction Limits Under Section 80CCD (or Section 124)
- Section 80CCD(1): Employee’s contribution to the National Pension System (NPS) qualifies for deduction within the overall limit of ₹1.5 lakh available under Section 80C. Under the Income-tax Act, 2025, this corresponds to Section 123.
- Section 80CCD(1B): An additional deduction of up to ₹50,000 is available for the employee’s NPS contribution over and above the Section 80C limit. Under the Income-tax Act, 2025, this corresponds to Section 124(3).
- Section 80CCD(2): Employer’s contribution to NPS is deductible up to:
- 10% of Basic Salary + Dearness Allowance (DA) under the old tax regime, or
- 14% of Basic Salary + Dearness Allowance (DA) under the new tax regime.
The aggregate tax-exempt employer contribution to NPS, Recognised Provident Fund (RPF), and Superannuation Fund is subject to an overall annual limit of ₹7.5 lakh. Under the Income-tax Act, 2025, this provision corresponds to Section 124(1).
However, this is only the starting point of the NPS journey.
Ironically, the tax deduction at the time of investment is also the benefit that receives the most attention, even though it may not be the most valuable one over the long term. The real strength of NPS lies in the fact that its tax efficiency doesn’t end after your contribution is made. It continues as your investments grow, your portfolio evolves, and eventually when you withdraw your retirement savings.
That’s where the second advantage becomes far more interesting—and far less understood.
Tax Advantage #2: Tax-free portfolio rebalancing
Markets are constantly changing, and so should your investment portfolio.
When you’re in your twenties or thirties, a higher allocation to equities may be appropriate because you have time on your side. As you move closer to retirement, however, gradually shifting a larger portion of your portfolio towards debt can help reduce risk and protect the wealth you’ve accumulated. This process of periodically adjusting the mix of equity and debt is known as portfolio rebalancing, and it is one of the fundamental principles of long-term investing.
In most market-linked investments, however, rebalancing often comes at a cost. Selling appreciated mutual funds, stocks or other investments triggers capital gains tax. While the tax may be justified, it also creates a behavioural challenge. Many investors postpone rebalancing—not because it isn’t financially sensible, but because they don’t want to incur an immediate tax liability.
Over time, this hesitation can leave portfolios carrying more equity risk than intended or prevent investors from making changes that better align with their financial goals and the market conditions.
This is where NPS offers a distinct advantage.
Permitted portfolio rebalancing within the NPS ecosystem does not attract capital gains tax. Whether you switch between equity and debt or change your pension fund manager under the applicable rules, these portfolio management decisions are not treated as taxable events.
As a result, your investment decisions can be guided by your financial goals, changing risk appetite and asset allocation strategy—not by the tax consequences of making a change.
In my view, this is the most overlooked aspect of NPS. Tax doesn’t just affect investment returns; it also influences investor behaviour. By removing tax as a barrier to portfolio rebalancing, NPS allows investors to make decisions that are financially appropriate throughout their retirement journey.
Under the commonly used Exempt-Exempt-Exempt (EEE) framework, the second ‘E’ typically refers to the fact that the investment returns accumulated within the NPS account are not subject to tax during the accumulation phase. While this is certainly an important benefit, the more significant advantage, in my view, is that investors can rebalance their portfolios without triggering capital gains tax. This allows changes in asset allocation to be driven by financial objectives, risk tolerance and market conditions, rather than by tax considerations—an aspect of NPS that is often overlooked but can have a meaningful impact on long-term retirement outcomes.
Tax Advantage #3: Tax-Efficient Exit and Withdrawal
The final advantage comes when you eventually retire or exit from NPS and begin using the wealth you’ve built.
Under the current NPS regulations, up to 60% of the accumulated corpus can be withdrawn as a tax-free lump sum. The remaining amount is typically used to purchase an annuity, with the purchase itself also enjoying favourable tax treatment under the prevailing framework.
Consider a simple example. Suppose your NPS corpus has grown to ₹2 crore at retirement. You may choose to withdraw ₹1.2 crore (60%) as a tax-free lump sum and use the remaining ₹80 lakh to purchase an annuity. Unlike many market-linked investments, there is no capital gains tax on the accumulated corpus at the time of withdrawal.
This completes what I call the Triple Tax Advantage of NPS. From the day you make your first contribution, through the years you manage your investments, to the day you retire, NPS remains one of the most tax-efficient retirement investment vehicles available in India.
Why the triple tax advantage matters
Most investors evaluate NPS based on the tax deduction they receive in a particular financial year. In reality, that is only one part of the story.
A retirement investment isn’t meant to be judged by a single transaction. It should be judged by how efficiently it helps you accumulate, manage and eventually access your retirement wealth over the next 25 or 30 years.
That’s what makes the Triple Tax Advantage of NPS so compelling. It doesn’t merely reduce your tax liability when you invest. It supports better investment decisions throughout your retirement journey by allowing you to rebalance your portfolio without tax friction and by providing favourable tax treatment when you retire.
Tax deductions may encourage you to begin investing. But it is tax-efficient wealth creation over decades that ultimately determines how much financial security your retirement corpus can provide. Viewed through that lens, NPS becomes much more than a tax-saving product—it becomes a long-term retirement planning solution.
The Question You Should Really Ask
Let’s go back to the question we started with.
“My annual income is below ₹12 lakh. I don’t really save much tax through NPS. Should I still invest?”
My answer would be yes.
If you’re early in your career, time is your biggest advantage. The tax deduction you receive today may be modest or zero, but you’re investing for the next 15 to 30 years—not for this financial year alone. Starting early gives your retirement corpus decades to compound, while allowing you to benefit from the Triple Tax Advantage of NPS throughout your investment journey.
If your employer offers Corporate NPS as part of a payroll-linked investing programme, it’s an opportunity worth considering. Regular contributions made directly through payroll help build financial discipline, while allowing you to take advantage of one of India’s most tax-efficient retirement investment structures.
The question, therefore, isn’t whether NPS saves enough tax today. It’s whether your future self will thank you for starting when time was still on your side.
If you’re looking to maximize NPS tax benefits while building a retirement corpus, starting early can significantly improve long-term outcomes.
This subject was also featured in Financial Express
Frequently Asked Questions
1. What are the tax benefits of NPS?
NPS can offer tax benefits at different stages of the investment journey. Eligible contributions can qualify for deductions under applicable provisions, employer contributions may receive tax benefits under Section 80CCD(2), and eligible withdrawals at exit receive favourable tax treatment under the prevailing rules.
2. Is NPS tax-free?
NPS offers tax benefits, but it is more accurate to say that specific contributions, withdrawals and other transactions receive favourable tax treatment subject to applicable rules. At normal exit, up to 60% of the accumulated corpus can generally be withdrawn as a tax-exempt lump sum, while the amount used to purchase an annuity is exempt at the point of purchase. The annuity income received subsequently is taxable according to the applicable tax rules.
3. What is the NPS tax benefit under Section 80CCD(1B)?
Eligible individual NPS contributions can qualify for an additional deduction of up to ₹50,000 under Section 80CCD(1B), subject to the applicable tax regime and prevailing provisions. This deduction is separate from the overall ₹1.5 lakh limit associated with Section 80C/80CCD(1).
4. What is the NPS tax benefit under Section 80CCD(2)?
Section 80CCD(2) provides a deduction for eligible employer contributions to an employee’s NPS account, subject to the applicable percentage limits and tax rules. The deduction is also available under the new tax regime, subject to the prevailing provisions.
5. Is NPS tax benefit available under the new tax regime?
Yes, but the available deductions differ from the old tax regime. Under the current tax framework, employer contributions eligible under Section 80CCD(2) can qualify for deduction under the new regime, while deductions such as 80CCD(1) and 80CCD(1B) are associated with the old regime.
6. Is the 60% NPS withdrawal tax-free?
At normal exit, up to 60% of the accumulated pension wealth can generally be withdrawn as a lump sum and is tax-exempt under the applicable provisions. The remaining portion is generally used for annuity purchase, and while the annuity purchase itself receives favourable tax treatment, the annuity income received later is taxable according to the applicable slab.
7. Does NPS attract capital gains tax when I change my investment allocation?
Permitted investment switches and portfolio rebalancing within NPS are not treated in the same way as selling and buying securities in a regular investment account for capital-gains taxation. This means eligible NPS portfolio changes can generally be made without a separate capital gains tax event. Your article’s emphasis on this as an often-overlooked feature is a useful differentiator.
8. What is the Triple Tax Advantage of NPS?
The Triple Tax Advantage is a way of looking at NPS tax efficiency across three stages: eligible tax benefits when contributions are made, tax-efficient portfolio management during the accumulation period, and favourable tax treatment at exit. It is an explanatory framework rather than an official tax classification.