The FIRE movement—Financial Independence, Retire Early—has brought an important idea into mainstream financial conversations: we should not spend our entire working lives being financially dependent on our next salary. By encouraging people to save more, invest early and think seriously about their long-term financial needs, FIRE has made financial independence an aspiration for a new generation of investors.
But there is a question we should ask before turning FIRE into a race towards a particular corpus or retirement age: Is early retirement really the objective of financial independence?
In most cases it is not.
The real value of financial independence is not necessarily the ability to stop working. It is the ability to make choices without being forced to make every decision around money. Retirement can be one outcome of financial independence, but it does not have to be the only one.
Financial independence should create freedom, not another target
The irony is that a movement designed to help people escape the financial treadmill can sometimes create another treadmill. Investors start calculating their FIRE number, tracking their savings rate and setting targets such as accumulating ₹5 crore by 40 or ₹10 crore by 45.
The corpus becomes the destination.
But there is no universal number that defines financial independence. The amount required for retirement depends on lifestyle, expenses, inflation, healthcare requirements, family responsibilities, longevity and the kind of life an individual wants to lead.
More importantly, financial freedom does not have to arrive on a particular date.
Someone who has accumulated enough investments to support several years of living expenses may not be ready for permanent retirement, but may already have significant financial freedom. That person may be able to leave an unpleasant job, take a sabbatical, accept a lower-paying but more fulfilling role, start a business or spend more time with family.
That is financial independence in action.
Think of financial freedom as a journey
Perhaps a more practical way to approach FIRE is to think about financial independence as a progression rather than an event.
The first milestone could be an adequate emergency fund and freedom from expensive debt. The next could be building investments that reduce dependence on monthly salary. As the investment corpus grows, an individual may gain the freedom to make increasingly significant career and lifestyle choices. Eventually, the corpus may become large enough to support life without active employment.
This approach makes retirement planning more meaningful because the purpose of investing is no longer limited to reaching a retirement number. It is about progressively buying yourself more choices.
The question changes from “When can I stop working?” to “When can I afford to work because I want to, rather than because I have to?”
Retirement planning needs to go beyond the FIRE number
This way of thinking also changes how one should build a retirement portfolio. Instead of starting with a headline corpus and working backwards, investors should first consider the life they want their money to support.
How much will they need every month? When do they want to reduce their dependence on active income? How much flexibility should they have during their working years? What happens if they live for 30 years after retirement? How much of their retirement income needs to be predictable?
These questions bring pension planning and annuity planning into the conversation.
Accumulating wealth is only one part of retirement planning. The second challenge is converting that wealth into sustainable income while managing inflation, longevity and market risks.
Where NPS can fit into the picture
The National Pension System (NPS) can be an important component of a long-term retirement strategy. NPS is often discussed primarily for its retirement purpose and NPS tax benefits, but it can also be considered as one building block within a broader retirement portfolio.
For salaried employees, Corporate NPS can make retirement accumulation more systematic by integrating long-term savings with the employment and payroll ecosystem. Applicable tax benefits can further improve its attractiveness as part of a long-term retirement strategy.
The important point, however, is not to view NPS in isolation. Retirement planning should consider the entire financial picture—NPS, provident fund savings, mutual funds and other investments—and how these different assets can eventually work together to create retirement income.
The objective should be to build a portfolio that gives you both financial security and financial flexibility.
Perhaps the “R” in FIRE needs to change
This brings us back to the idea behind FIRE.
Financial Independence is a powerful goal. But Retire Early is only one way of using that financial independence.
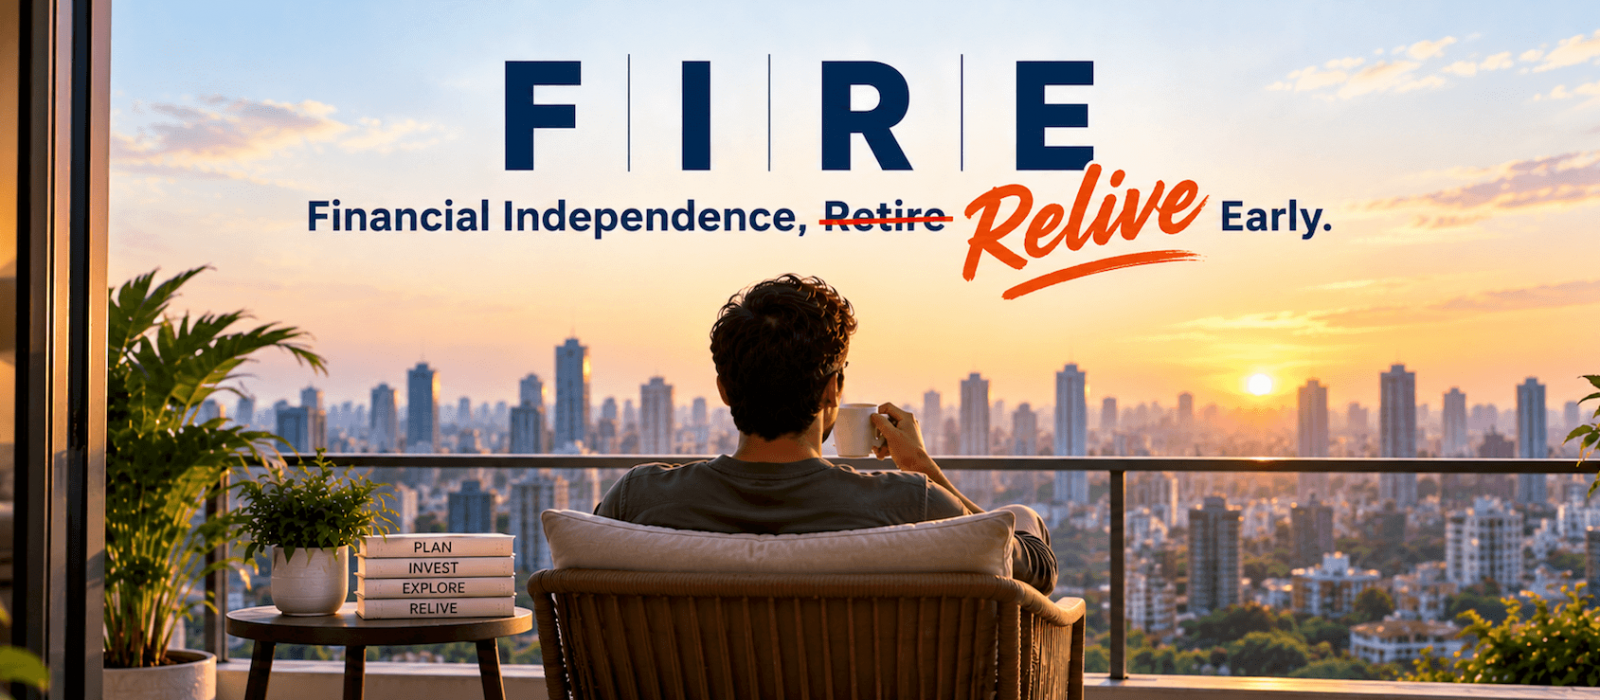
What if FIRE could instead mean Financial Independence, Relive Early?
Relive the experiences that work and financial responsibilities often force us to postpone. Take a sabbatical while you are still young. Spend more time with your children while they are growing up. Change careers. Travel. Start something of your own. Pursue an interest that you kept aside because it did not make financial sense.
You don’t necessarily need to wait until retirement to start living differently.
The purpose of good retirement planning, pension planning and long-term investing should not simply be to accumulate the largest possible corpus or retire at the youngest possible age. It should be to create enough financial freedom that your choices are no longer dictated entirely by your need for income.
Don’t FIRE to Retire. FIRE to Relive.
This subject was also featured in Outlook Money.