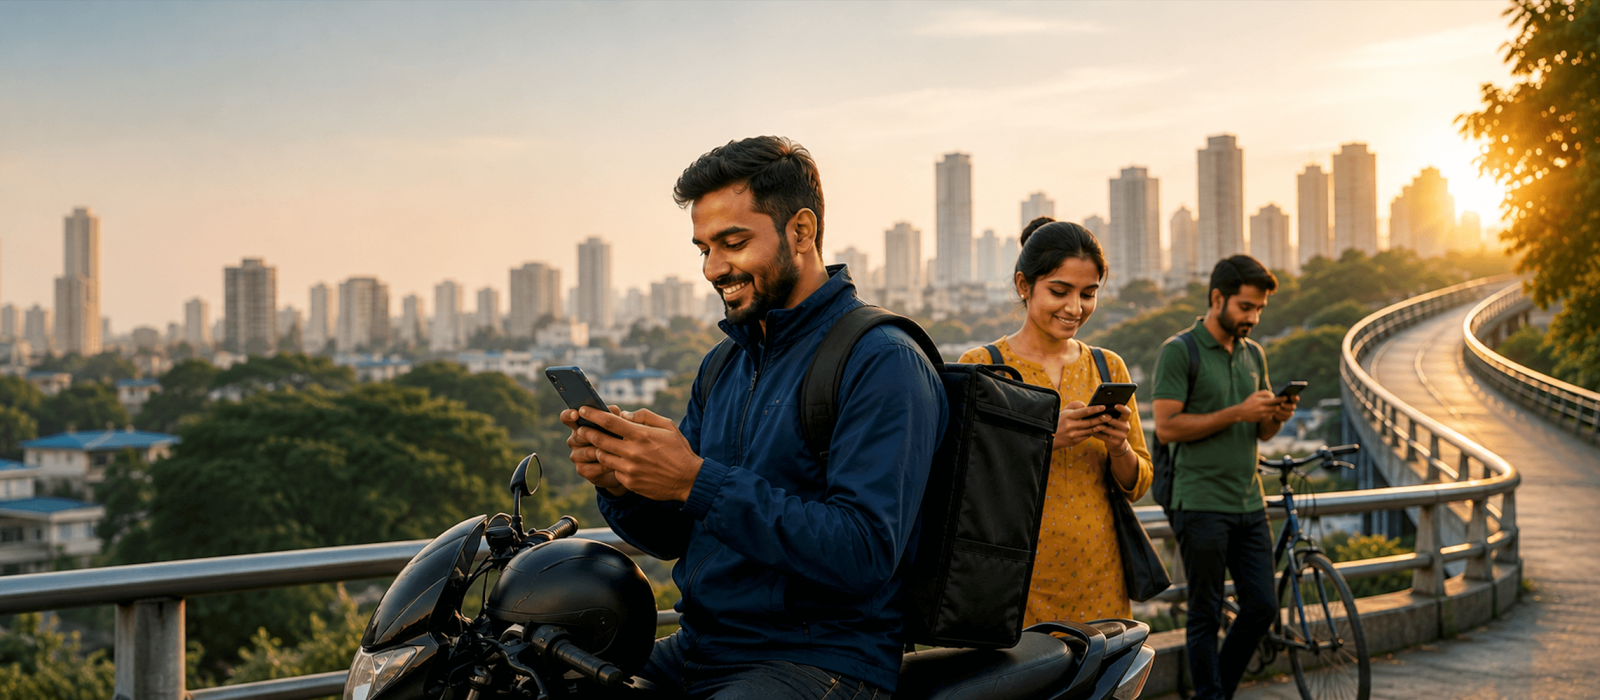
India’s platform economy has changed how millions of people earn. A delivery partner can receive earnings digitally, access credit through a smartphone and complete financial transactions without ever visiting a bank.
Yet when it comes to retirement, that same worker may have no structured system quietly building financial security for the years when active income stops.
The gig economy has solved how people earn. The next challenge is helping platform workers build financial security from those earnings.
This is where the conversation around retirement benefits for gig workers and platform workers needs to move beyond access and towards architecture.
Why platform workers need a different retirement model
Traditional employment has a built-in advantage when it comes to retirement planning. A salaried employee receives a predictable monthly income, and benefits such as EPF or Corporate NPS can make long-term investing part of the employment journey.
Platform workers need a more sustainable approach to security for gig workers, including retirement savings and long-term financial protection.
Platform workers operate differently.
Their earnings can vary from one week to another. A strong week can be followed by a weak one, while an unexpected expense can immediately take priority over retirement savings. Asking a gig worker to commit to a fixed monthly investment may therefore not always be the most effective way to encourage long-term saving.
The answer may not be to ask a gig worker to save more. It may be to make retirement saving fit the way they earn.
This creates an important role for companies and platforms that engage gig workers. They do not necessarily have to fund the entire retirement benefit themselves. Their more important role could be to make retirement investing easier, more accessible and more closely connected to the worker’s earnings pattern.
Instead of requiring a worker to make a fresh investment decision every month, contributions could be linked to earnings. A percentage of each payout or pay cycle could flow towards retirement, allowing contributions to rise when earnings are higher and reduce naturally during weaker periods.
The underlying principle is simple: Retirement saving should move with income, rather than compete with it.
National Pension System (NPS) as retirement security for platform workers
There is already a useful model of within the formal workforce: Corporate NPS.
Corporate NPS brings retirement investing into the employment ecosystem, allowing employers to facilitate long-term retirement savings through the payroll-linked investing. The opportunity now is to adapt the underlying principle for a workforce whose earnings do not follow a predictable monthly salary.
The recent evolution of NPS, including the e-Shramik framework for platform service partners, makes this conversation even more relevant. Pension Fund Managers can curate schemes suited to the needs of this workforce, including options for workers with different risk appetites.
This is not about making gig workers behave like salaried employees.
It is about building a retirement system that works with the way platform workers actually earn.
This is also where initiatives such as Floatr’s GigRise can play an enabling role—connecting the earning journey of platform workers with access to structured retirement investing and financial wellness.
For employers and platforms that engage gig workers, retirement benefits can increasingly become part of a broader financial security proposition. The objective is not necessarily to replicate every benefit available to salaried employees, but to remove the friction that prevents workers from beginning to build long-term financial assets.
That has implications far beyond retirement.
India has spent years expanding financial inclusion through bank accounts, digital payments and access to formal financial services. The next phase of financial inclusion should be about helping people convert that access into financial assets and long-term financial security.
A worker who can receive money digitally should also have an equally simple pathway to build retirement wealth from that income.
Financial inclusion cannot end with access to financial services. It should ultimately help people build financial security.
For a platform worker who has never had an EPF account or a structured retirement benefit, making the first retirement contribution as easy as receiving the first payout could be one of the most meaningful steps towards genuine financial inclusion.
The future of India’s gig economy
The future of India’s gig economy will not only be measured by how many people it enables to earn.
It should also be measured by whether those earnings can help workers build a financially secure future.