The National Pension System (NPS) is a long-term retirement savings system that helps individuals build a retirement corpus during their working years. While an individual can open an NPS account independently, NPS can also be offered through an employer as an employee benefit. This is known as Corporate NPS or the NPS Corporate Sector Model.
In simple terms, Corporate NPS allows a company to make retirement saving a part of its employee benefits programme, with contributions being made by the employer, employee, or both.
It can complement existing retirement benefits such as EPF, gratuity and superannuation, while giving employees another structured way to build long-term retirement wealth.
How does Corporate NPS work?
Corporate NPS was introduced in 2011 to bring NPS into the organised sector. It is regulated by the Pension Fund Regulatory and Development Authority (PFRDA) and operates through a regulated ecosystem of pension fund managers, recordkeeping agencies and other intermediaries.
When a company adopts Corporate NPS, eligible employees can enrol and receive a Permanent Retirement Account Number (PRAN). The PRAN identifies the employee’s NPS account and stays with the subscriber through their working life.
The employer can decide how NPS will be incorporated into its benefits structure. For example, the company may make a defined contribution towards NPS as part of the employee’s compensation. Employees may also make their own contributions, depending on the company’s policy.
The contributions are invested in market-linked pension schemes selected by the employees themselves under the applicable NPS framework.
What is payroll-linked investing?
One of the important advantages of Corporate NPS is that retirement investing can become payroll-linked investing.
Instead of an employee having to remember to make a separate investment every month, the contribution can be integrated with the payroll and benefits process. This makes long-term investing more systematic and reduces the effort involved in managing retirement savings.
This is also why Corporate NPS can be particularly relevant for employers looking at payroll-linked employee benefits and corporate financial wellness.
For employees, it brings retirement saving into the same system through which they receive their salary and other benefits. For employers, it provides a structured way to offer a long-term financial benefit without having to create and manage their own pension investment infrastructure.
Who contributes to Corporate NPS?
Corporate NPS gives employers flexibility in deciding how contributions will work. A company can contribute to an employee’s NPS account, the employee can make their own contribution, or both can contribute.
In the private sector, one of the more common approaches is to offer the employer’s NPS contribution as part of the employee’s flexible benefits or flexi-benefit structure. Instead of treating NPS as an additional cost over and above the employee’s salary package, the employer can structure a portion of the employee’s overall compensation towards NPS, subject to the company’s policy and applicable tax rules.
For example, an employee may be offered the choice to allocate a specified portion of their salary or benefits towards NPS. Once the employee opts for it, the contribution can be processed through payroll and credited to the employee’s NPS account.
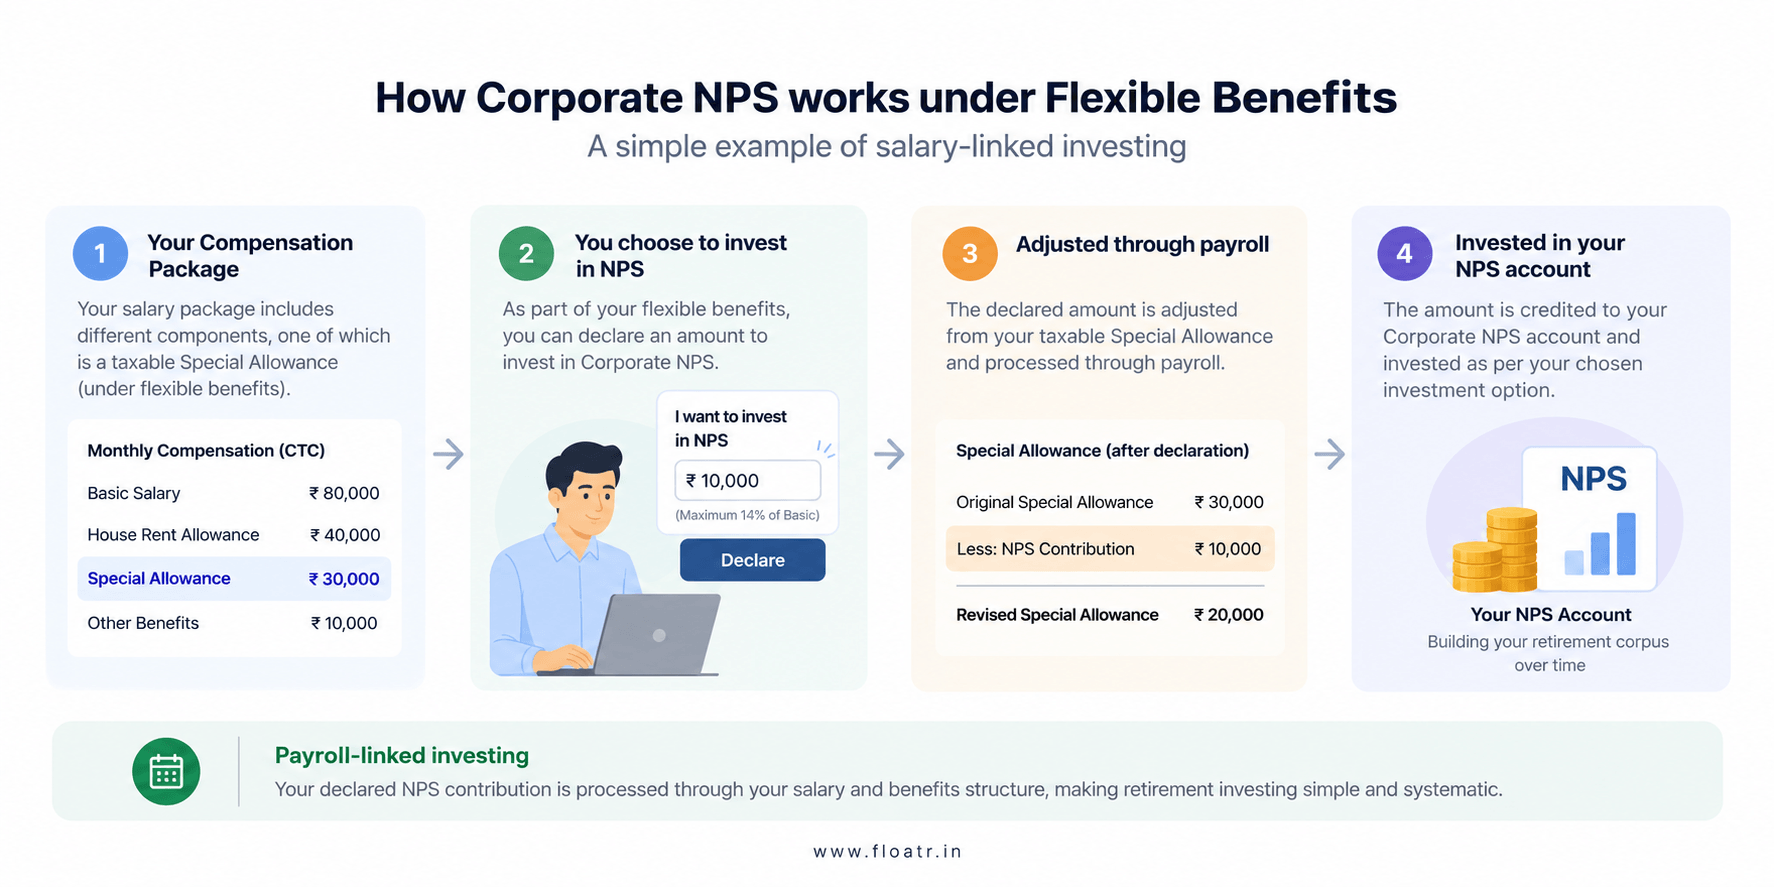
This creates what can be described as payroll-linked investing or salary-linked investing—where an investment happens alongside the salary process rather than requiring the employee to separately initiate it every month.
Some employers may also make an additional NPS contribution as an employee benefit. The exact structure can therefore vary from company to company. One organisation may offer NPS as a component of its flexible benefits, while another may provide an employer contribution as part of its compensation package.
For employees, this distinction is important. When NPS is offered through a flexible benefits structure, the employee should understand whether the contribution is coming from an existing component of their compensation or is an additional benefit provided by the employer. The tax treatment can also differ depending on how the contribution is structured.
This flexibility is one of the reasons Corporate NPS can fit naturally into modern employee-benefit programmes. It allows employers to incorporate retirement investing into the existing payroll and benefits architecture while giving employees a simple way to build their retirement corpus over their working years.
What are the investment options in NPS?
NPS is not a conventional fixed-return pension product. The contributions are invested in market-linked pension schemes.
Subscribers can choose how their retirement corpus is allocated across permitted asset classes and investment options under the NPS framework. These can include equity, corporate debt and government securities, depending on the applicable scheme and investment choice.
This means an employee can build an NPS portfolio based on their investment horizon, financial goals and risk appetite.
The NPS framework has also evolved over time, giving non-government subscribers greater choice in selecting investment schemes. This makes it possible to look at NPS as part of a broader retirement planning strategy rather than simply as a pension account.
What are the tax benefits of Corporate NPS?
Tax benefits are an important part of the Corporate NPS proposition.
Employer contributions to NPS can qualify for a tax deduction under Section 80CCD(2) of the Income Tax Act, subject to the applicable conditions and limits. Under the Income Tax Act, 2025, the corresponding provision is covered under Section 124.
The actual tax benefit available to an employee depends on factors such as their salary structure and the amount contributed by the employer. Importantly, the tax benefit on eligible employer contributions to NPS is available under both the old and new tax regimes, subject to the applicable limits and conditions.
NPS also has a significant triple tax benefit across the investment journey—covering the tax treatment of contributions, switching or rebalancing within NPS, and the applicable treatment at exit.
Employees should, however, evaluate the tax benefit based on their own salary structure and applicable tax provisions rather than assuming that every contribution receives identical tax treatment.
Corporate NPS vs Individual NPS
The underlying NPS framework is broadly the same, but the way the account is accessed is different.
With individual NPS, a person opens and manages the account independently and makes contributions directly.
With Corporate NPS, the employer first adopts NPS for its employees. Employees can then enrol through the organisation, with contributions potentially being integrated with the company’s payroll and benefits process.
Your NPS account travels with you, not with your employer. Changing jobs does not mean withdrawing your accumulated NPS corpus or opening a new PRAN. Your existing NPS account continues with you as you move from one employer to another, subject to the applicable process.
Why should employers offer Corporate NPS?
For employers, Corporate NPS can be more than another investment option. It can become part of a company’s broader employee financial wellness strategy.
Retirement is one of the largest long-term financial goals for most employees, but it is often postponed because it competes with immediate financial priorities. Making retirement saving part of the workplace benefits structure can help employees start earlier and invest more consistently.
For the employer, a Corporate NPS platform or Corporate NPS service provider can help simplify implementation, employee onboarding, contribution processing and ongoing administration.
For employees, the benefit is equally straightforward: a dedicated retirement investment that can receive regular contributions throughout their working life, potentially including contributions from their employer.
Ultimately, Corporate NPS brings retirement planning into the workplace. It combines the convenience of payroll-linked investing with the long-term investment framework of NPS, while providing employers with a structured retirement benefit to support their employees’ financial security.