Managing a retirement account should not be complicated. Yet, for many National Pension System (NPS) subscribers, accessing account information, understanding investment choices and navigating different service providers can sometimes feel like separate tasks.
The Pension Fund Regulatory and Development Authority (PFRDA) has taken an important step towards simplifying this experience with the launch of NPS Central, a unified digital platform designed to bring key NPS services together under one interface.
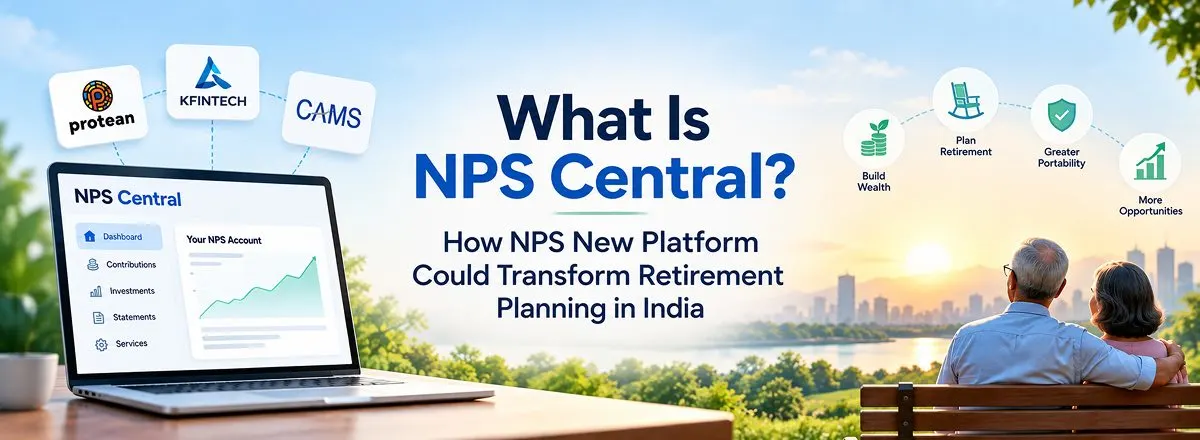
The platform went live in October 2026 and it brings together the three Central Recordkeeping Agencies (CRAs)—Protean, KFintech and CAMS—through a common digital interface.
For subscribers, this means easier access to pension services. For the broader retirement ecosystem, however, the opportunity could be much larger: moving from simply managing pension accounts to helping people make better-informed retirement decisions.
What is NPS Central?
NPS Central is a digital platform that aims to make it easier for National Pension System subscribers to enrol, access and manage their pension accounts.
Until now, a subscriber’s experience has often depended on which CRA maintains their NPS account. These agencies handle important functions such as recordkeeping, transaction administration, account statements and subscriber services.
NPS Central introduces a common access point across all three CRAs, helping reduce the need to navigate separate service-provider portals.
This is particularly relevant for employees who change jobs, individuals who move between employment categories, and subscribers who may not remember which agency maintains their account.
The broader objective is to make NPS more accessible, convenient and subscriber-centric.
Key features and benefits of the NPS Central portal
The significance of NPS Central lies in the services it brings together and the scope for further integration.
1. A single digital interface for NPS services
Subscribers can access key NPS services through a common platform instead of having to identify and navigate the relevant CRA portal for every requirement.
This can make routine activities such as accessing account information, reviewing investments and managing pension-related services more convenient.
2. Easier onboarding for new NPS subscribers
A simpler digital journey can reduce the friction involved in joining NPS. New subscribers can explore available options and complete eligible digital onboarding steps through the platform.
A more accessible onboarding experience can help bring retirement investing to individuals who may otherwise postpone opening an account because the process seems complicated.
3. Better access to investment information
NPS is a long-term investment product, and subscribers need to understand more than just their account balance.
Access to scheme information, investment choices and historical performance can help subscribers become more informed about how their retirement savings are invested.
The next opportunity is to make this information easier to compare and interpret, especially for first-time investors who may find pension fund and scheme terminology difficult to understand.
4. Greater convenience when employment changes
Changing employers does not, by itself, mean that a subscriber must abandon their accumulated NPS savings. However, moving between employers and Corporate NPS arrangements can involve administrative requirements.
A common digital interface can make it easier for subscribers to access their pension information during these transitions.
In the longer term, smoother interoperability across CRAs and employment categories could further improve the portability of the NPS experience. A unified interface alone, however, should not be mistaken for a guarantee that every CRA migration or account-transfer process is already seamless.
5. More accessible account servicing and grievance support
A consolidated platform can make it easier for subscribers to locate account services, review contributions, access statements and find appropriate grievance-redressal channels.
For employees, this can also support better visibility into their retirement contributions and help them verify whether expected employer contributions have been credited.
NPS Central and the three CRAs: Why does this integration matter?
The integration of Protean, KFintech and CAMS is an important step towards a more connected NPS ecosystem.
Each CRA performs an essential recordkeeping and servicing role. Bringing their services together through a common interface can reduce the administrative fragmentation experienced by subscribers.
A useful comparison is MF Central, which provides a common interface for accessing participating mutual fund investments across the mutual fund ecosystem.
NPS Central has the potential to deliver a similar degree of convenience for pension account access, while addressing the specific requirements of a regulated retirement system.
The important distinction is that a common interface is the beginning of interoperability, not the end of it.
For the experience to become truly seamless, subscribers should eventually be able to move between relevant services without having to understand the underlying institutional boundaries.
The next big opportunity: Moving from account management to retirement planning
This is where the evolution of NPS Central could become particularly meaningful.
For many subscribers, retirement planning is still reduced to a simple question: How much money have I accumulated?
But a corpus figure alone cannot tell an individual whether they are on track to retire comfortably.
A meaningful retirement-planning experience should help subscribers answer five questions:
- Am I saving enough? Assess whether the current contribution rate is likely to build a sufficient retirement corpus.
- How is my money invested? Understand the allocation between equity, corporate debt and government securities, where applicable.
- Are my investments performing as expected? Review investment performance in the context of risk, time horizon and retirement goals.
- When could I realistically retire? Estimate retirement readiness using current savings, future contributions, inflation and expected expenses.
- How will I generate income after retirement? Understand the potential role of accumulated pension wealth, lump-sum withdrawals and annuity or other permitted retirement-income options.
These capabilities would take NPS Central beyond being a convenient service portal and towards becoming a more useful digital companion throughout an individual’s retirement journey.
Some of these functions would require additional development and integration beyond account access and servicing. Personalised retirement projections, in particular, would be a valuable future enhancement.
NPS Central and PRIDE-DISHA: The case for connecting information with action
Another promising opportunity is the integration of NPS Central with PRIDE-DISHA, PFRDA’s pension information and analytical initiative.
Historical performance information can help subscribers compare pension funds and understand investment outcomes. But data is most useful when individuals can connect it to their own investment decisions.
An integrated experience could allow subscribers to explore historical fund performance, understand the available choices and then access the relevant account services without navigating multiple platforms.
Over time, such integration could help bridge the gap between investment information and investment action.
It would also be important to present comparisons responsibly. Historical returns should not be interpreted as guaranteed future performance, and scheme comparisons should consider investment risk, asset allocation and the subscriber’s time horizon.
What NPS Central could mean for Corporate NPS and employers
The benefits of a more integrated NPS ecosystem extend beyond individual subscribers.
For employers offering Corporate NPS, the quality of the employee experience can influence how easily the benefit is understood, adopted and managed.
A simpler account-access journey could help employees engage more actively with their pension savings. Better visibility into contributions and account information could also make routine servicing easier.
The next opportunity is to simplify the journey when employees join a new organisation, move between Corporate NPS arrangements or need assistance with account-related processes.
For HR and payroll teams, clearer digital journeys and fewer avoidable service queries could make Corporate NPS easier to communicate and administer.
However, a unified portal does not automatically eliminate employer-level onboarding, contribution-remittance or CRA-transition requirements. Those processes will depend on the applicable framework and the capabilities enabled on the platform.
What should the next phase of NPS Central focus on?
For NPS Central to realise its full potential, the focus should progressively shift from bringing services together to making the entire retirement journey easier to navigate.
Four developments could make a meaningful difference.
1. Seamless CRA portability
Subscribers should ideally be able to move between relevant CRA arrangements through a transparent, digitally enabled process, subject to the applicable rules and operational requirements.
2. Integrated investment comparison
Historical returns, scheme characteristics, charges and investment choices should be presented in a way that helps subscribers make informed comparisons rather than simply view data.
3. Personalised retirement-readiness tools
A retirement calculator or projection engine could help individuals understand whether their current savings trajectory is sufficient, what adjustments may be required and how different retirement ages could affect their financial outlook.
4. A smoother retirement-income and exit journey
Retirement is the stage at which pension savings must begin supporting real-life expenses. Easier access to information and processes relating to eligible exits, lump-sum withdrawals, annuity selection and applicable Retirement Income Scheme options could make this transition less daunting.
These are opportunities for the platform’s future evolution, not a claim that all these capabilities are currently available through NPS Central.
What should NPS subscribers do now?
Subscribers can begin by using the available NPS Central services to familiarise themselves with the platform and review their pension account information. An existing NPS subscriber can simply login to NPS Central using their PRAN linked mobile number.
They should also periodically:
- Check whether their contributions have been credited correctly.
- Review their current investment choices and asset allocation.
- Understand the historical performance of their chosen schemes without treating past returns as a forecast.
- Reassess their retirement goals, expected expenses and savings rate.
- Review the applicable withdrawal and retirement-income rules as retirement approaches.
The key is not to make frequent investment changes simply because a new digital platform is available. It is to use better access to information to make more considered decisions aligned with personal circumstances and long-term goals.
The bigger picture: Making retirement planning more accessible
NPS Central is an important step towards simplifying access to the National Pension System. Bringing three CRAs together under one digital interface can reduce friction, improve convenience and make pension services easier to navigate.
But the larger opportunity lies ahead.
A genuinely subscriber-centric retirement ecosystem should help people not only access their accounts, but also understand their investments, assess their retirement readiness and navigate the transition from accumulating savings to generating retirement income.
That is the next frontier for digital pension infrastructure in India: moving from managing a pension account to helping people plan for retirement with greater clarity and confidence.
As the platform evolves, its success will depend not just on the number of services available in one place, but on how effectively those services help subscribers make better decisions over the course of their working lives and into retirement.
Frequently asked questions about NPS Central
1. What is NPS Central?
NPS Central is a unified digital platform launched by PFRDA to provide a common interface for National Pension System subscribers to enrol, access and manage pension-related services.
2. Which CRAs are integrated with NPS Central?
The platform brings together the three NPS Central Recordkeeping Agencies: Protean, KFintech and CAMS.
3. What are the main benefits of NPS Central?
Its key benefits include a common access point for pension services, a more convenient onboarding experience, easier access to account and investment information, and the potential to simplify subscriber servicing across the NPS ecosystem.
4. Can I change my NPS pension fund through NPS Central?
Investment-choice changes are an area of development for the platform. Subscribers should check the currently enabled services and applicable rules before initiating a change.
5. Does NPS Central make it possible to switch CRAs seamlessly?
The common interface is a step towards better interoperability, but it does not by itself guarantee that every CRA migration is available or seamless. Subscribers should verify the current functionality and applicable process.
6. Will NPS Central help me plan my retirement?
The platform can improve access to pension and investment information. Personalised retirement projections and integrated retirement-readiness tools would be valuable future enhancements, but subscribers should verify which planning features are currently available.
7. How can Corporate NPS subscribers benefit from NPS Central?
A more convenient account-access experience can help employees review their pension information and contributions. Further integration of employer-related processes and CRA transitions could make Corporate NPS easier to manage over time.
8. How can I login to NPS Central?
Subscribers can visit the official portal at www.npscentral.in and login using the mobile number that is linked to their PRAN. You can login and check the services currently available to them.